


There is no respite for MAPFRE MSV LIFE PLC, the embattled fund owned by the insurer Mapfre in Malta, which is locally owned by Bank of Valletta. The fund has been hit with multiple orders by the financial tribunal to provide compensation to litigating clients who claim they have been over-promised bonuses and returns which were not provided.
The tribunal is awarding compensation of around €3,000 to €3,400 to claimants who expected maturity payouts of up to €48,000 and €55,000, but received offers of around €20,500 and €22,300 instead after twenty years and more after having made their initial investment. The argument is that the original projections were not legally guaranteed, despite the expectations they created among policyholders.
The problem with Mapfre is that they based their performance on future income from clients’ funds rather than at making any money at all. In fact, one of the financial advisors assisting Mapfre clients, Paul Bonello is now asking the fund whether the current payouts as enforced by the tribunal are being funded by clients’ funds instead of by the earnings made.
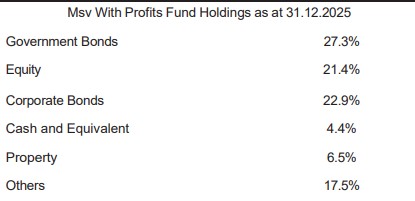
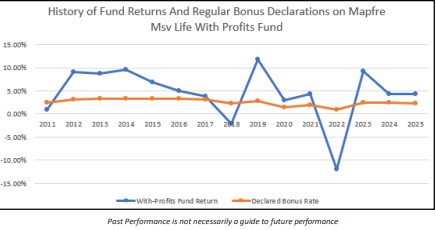
The funds still perform very poorly despite running marketing campaigns to entice clients. According to MAPFRE’s official announcement on 18 March 2026, the fund achieved an investment return of 4.37% in 2025, while the regular bonus declared for 2025 was 2.35% on its core products and 2.25% on the Comprehensive Life Plan. The fund has made an annualised return of 2.25% in the last ten years and this is very disappointing.
The current investment committee chairman is Romeo Cutajar – an ex-trader and investment manager at Bank of Valletta: a bank which has a very consistent track-record of funds that under-perform. My impression is that the current BOV Chairman would like to replace the bank’s weak performance of its funds by focusing more on its core holdings of government debt and US Treasuries, which would be a very sensible decision to take in a high-interest rate environment when your fund mangers have consistently underperformed.
The biggest underlying political and economic risk behind this disastrous mess is that any government will find it very challenging to introduce a social security policy based on private investments if the major life-insurance funds of the major financial and banking institutions of the country are a disastrous mess.
The latest BOV Chairman Gordon Chairman has successfully cut the bank’s risk and weaned off a lot of garbage from its credit books. He increased his focus on the bank’s core security holdings of public and government debt to fatten its books. All of this is very clear. However, the bank and its insurance arm are projecting a very vampiric and rent-seeking relationship with the public – even if this may seem in the interest of the financial and banking institution by someone who has worked at the bank for all of their lives, this attitude and culture is toxic and is ultimately degrading the reputation of the financial sector along with the notion of long-term investing in financial securities.
These financial institutions have an important and positive role to play in society. Mapfre should begin viewing itself as an institution that can provide positive value to society rather than remain this toxic train-wreck draining people’s money for no end at all other than to simply survive as a mediocre entity.
You can find some of the Financial Arbiter’s decision here, here and here.

Website Editor
Historian and Publisher
Leave a Reply