There’s a very definite and material reason why Yorgen Fenech chose to kill Daphne Caruana Galizia and it wasn’t just because he feared being outed for his corruption with Keith Schembri, Konrad Mizzi and Joseph Muscat via his secret company 17 Black.
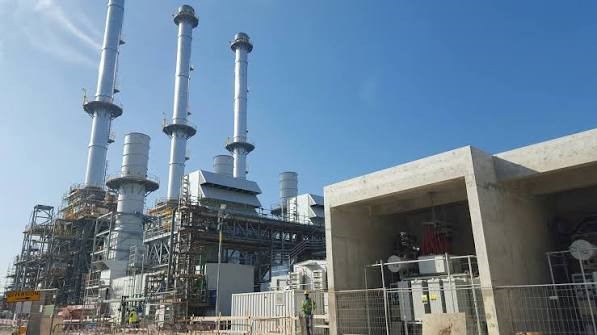
In early 2017, especially by February, Electrogas faced a severe cash-flow crisis. Its bank balance had fallen from hundreds of millions of euros to around €100,000, it was struggling to pay creditors and staff, and it risked defaulting on its existing facilities.
At that stage the project was still running on a €450 million bridge loan led by Bank of Valletta, with HSBC, Société Générale and KfW IPEX-Bank also participating. The Maltese government had guaranteed 80 per cent of that loan (€360 million).
The guarantee was secretly extended in May 2017 and again after banks notified a “serious default” in September 2017, buying the consortium more time.
Long-term refinancing was only completed in late December 2017. An expanded group of lenders then provided senior debt of roughly €400–500 million. In addition to Bank of Valletta, HSBC, Société Générale and KfW IPEX-Bank, the new participants included Natixis, BNP Paribas Fortis, Crédit Industriel et Commercial (CIC), DZ Bank, Rivage Investment and Arguin Infrastructure Partners. Once this package closed, the government withdrew its €360 million guarantee.
Daphne’s investigations could have compromised the financing of the project, so in order to save the project, they had to mmurder Daphne to ensure they could secure the credit for the project.
Read below the assessment by Luke Frendo, who specialises in credit management and risk, on why Electrogas risked losing its financing options if Daphne had went ahead with her investigation.
Start of message by Luke Frendo.
For the first years of my career, I worked for Deutsche Bank. For much of that period, I was responsible for managing the bank’s credit risk to a number of countries, including Malta. Had I still been at the bank in 2017, and had Deutsche Bank been approached to participate in the Electrogas financing, the transaction would likely have crossed my desk. I therefore have some understanding of how a major international bank would have assessed the risks involved in participating in such a financing.
Over the last few days, I revisited the details of Electrogas and 17 Black. I had forgotten much of them, including just how consequential the 17 Black revelations might have been had they emerged before Electrogas secured its long-term financing.
A revelation connecting Yorgen Fenech – and, by extension, Electrogas – to 17 Black before the long-term financing was completed could have seriously jeopardised that financing. For major international banks, Malta represented an inconsequential commercial opportunity. The emergence of significant corruption, money-laundering or reputational concerns surrounding a key participant in the project could therefore have changed the risk-reward calculation dramatically. A bank did not need to establish that anything illegal had occurred; serious unresolved compliance and reputational concerns could themselves have been enough to simply walk away.
For Electrogas, therefore, the consequences of a failed or substantially delayed refinancing could have been catastrophic. And Daphne’s investigations were getting dangerously close to making this happen.
1. Daphne Caruana Galizia first revealed the existence of 17 Black in February 2017. At that point, however, she did not publicly connect the company to Yorgen Fenech, and therefore there was no public connection between 17 Black and Electrogas.
2. During this period, Electrogas had yet to secure the long-term bank financing required to refinance its roughly €450 million bridge facility. Its ability to survive depended on that refinancing.
3. Part of the problem was timing. EU approval was required before the Government could enter into what’s called a Security of Supply Agreement, and long-term financing depended on this.
4. The Government guarantee, originally intended as a temporary measure, was due to expire on 31 May 2017.
5. On 1 May, an early general election was called for 3 June 2017.
6. On 24 May, the Government extended its guarantee supporting Electrogas’ financing. The State consequently remained exposed for more than €400 million in the event of a default.
7. Daphne Caruana Galizia was murdered on 16 October 2017.
8. Electrogas completed its long-term refinancing on 29 December 2017, allowing the Government guarantee to be released.
9. Yorgen Fenech was publicly identified as the owner of 17 Black only in November 2018, almost a year after the refinancing had been locked in.
That sequence is important.
Had Fenech’s ownership of 17 Black become public before 29 December 2017, the international banks financing Electrogas could have walked away.
No one can say with certainty that the banks would have withdrawn. But it is entirely plausible that they may have suspended the transaction, demanded substantially enhanced due diligence or declined to proceed. Given Electrogas’ dependence on completing the refinancing, even a significant delay could have had profound consequences for the company and, because of the State guarantee, for the Government.
Seen in isolation, the identity of the beneficial owner of 17 Black might appear a relatively minor revelation. In the context of Electrogas’ precarious financing position in 2017, however, it had the potential to be enormously consequential.
And Daphne Caruana Galizia was murdered precisely in the middle of that critical period.
Website Editor
Historian and Publisher





Leave a Reply